
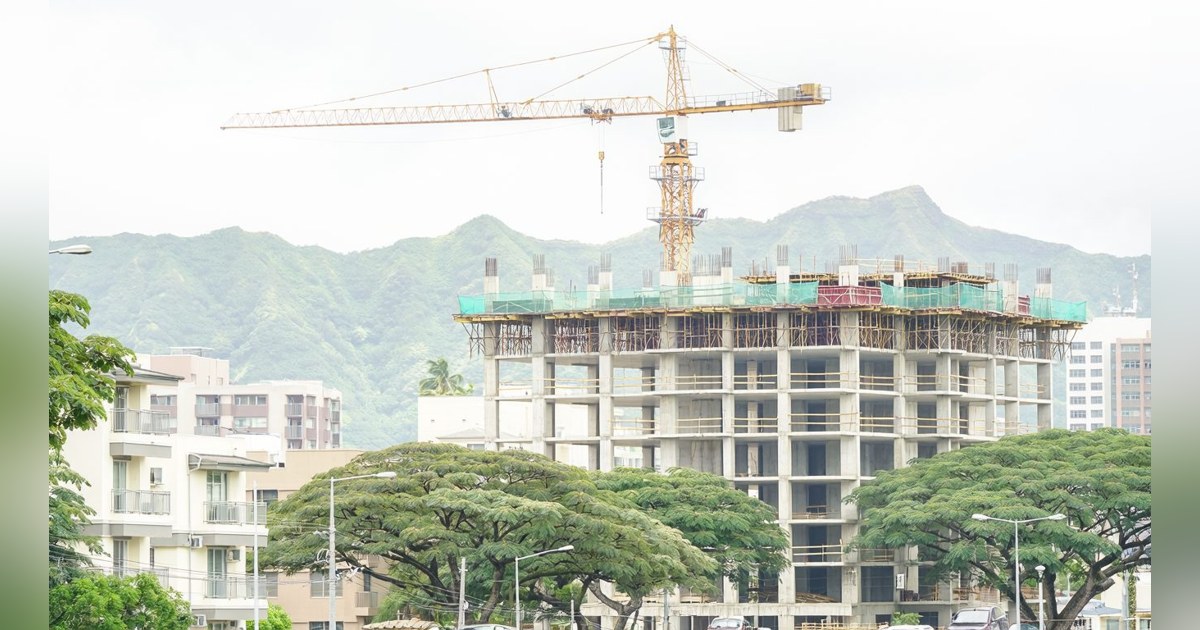
Housing legislation debates in Hawaii often fixate on density numbers—how many units a parcel can hold, how tall a building can rise, how much floor area a site can support. Those figures attract headlines, but for developers underwriting projects in Honolulu, a different variable carries more weight: whether a project can be approved as of right. This distinction is why Bill 18 has drawn significant attention.
Currently, most market-rate residential development on Oahu proceeds through the 201H process, which functions as a form of spot zoning. Developers navigate a political pathway involving neighborhood boards, public hearings, and consultations whose outcomes are unpredictable when capital is committed. According to Mike Perkins of The Bratton Team at Colliers International Hawaii, this introduces substantial uncertainty. “It provides a lot of uncertainty to the process,” Perkins says. That uncertainty is priced conservatively because carrying land through an indeterminate approval period imposes costs with no defined endpoint.
Bill 18, introduced by Council Vice Chair Andria Tupola, would expand the Chapter 32 Affordable Rental Housing program—known as Bill 7 after the 2019 ordinance—into apartment, apartment mixed-use, business, and business mixed-use zoning districts, along with the apartment precinct of Waikiki. The program offers relaxed zoning standards, property tax relief, and fee waivers in exchange for at least 80% of units being rented for a minimum of 15 years at rates affordable to households at or below 100% of area median income. For 2026, that threshold is $93,400 for a single person and $133,400 for a family of four. Successive drafts have also addressed lot area limits, replaced the blanket 60-foot height cap with underlying zoning heights, allowed additional units near high-service bus stops within the Primary Urban Center Development Plan area, and repealed maximum square footage rules.
While density provisions help by improving floor area ratios and allowing larger lot assemblies, Perkins identifies the decisive provision as Chapter 32 projects proceeding directly to the building permit process. Developers would know at the outset what is permitted and could proceed accordingly. The financial impact is substantial: certainty compresses timelines, reduces carry costs, and lowers the cost of capital. A shorter, more predictable path also widens the pool of capital willing to participate, as the risk shifts from political to construction and lease-up. “That in and of itself would help speed up the process,” Perkins notes. Timing is critical, given Honolulu’s requirement for 27,710 new units between 2023 and 2027, a figure that demands pathways measured in months, not years.
Two other regulatory developments are shaping investor perspectives. On Maui, Bill 9 phases out short-term rental use in apartment-zoned condominiums, while Bill 88, passed in June, created the H-3 and H-4 rezoning pathway. Values in apartment-zoned and hotel-zoned product have diverged, becoming a live consideration in underwriting across both counties. Additionally, every Hawaii county must permit two accessory dwelling units per lot by the end of the year under a 2024 state law, which Perkins assesses primarily affects the single-family side, supporting housing stock without materially impacting commercial-scale multifamily development.
Asked whether regulatory clarity now weighs more heavily in underwriting Hawaii income property than interest rates, Perkins is unequivocal: it does. Entitled land carries a similar question, as buyers may need to reaffirm entitlements, introducing time costs that are discounted. Bill 18 matters beyond the affordable segment because converting a discretionary process into a defined one removes a discount that currently applies market-wide. For developers and investors, the regulatory pathway attached to a site belongs alongside physical characteristics in any valuation. Two parcels with identical zoning and dimensions are not equivalent if one qualifies for a by-right pathway and the other requires discretionary approval. The difference shows up in carry cost, financing terms, and buyer pool breadth. Current Hawaii inventory and monthly market statistics describe what is available and how it is pricing, but knowing which approval pathway attaches to a position is what turns that into an investment decision. As Hawaii’s approval framework becomes more defined, sites positioned to use it stand to benefit first.