
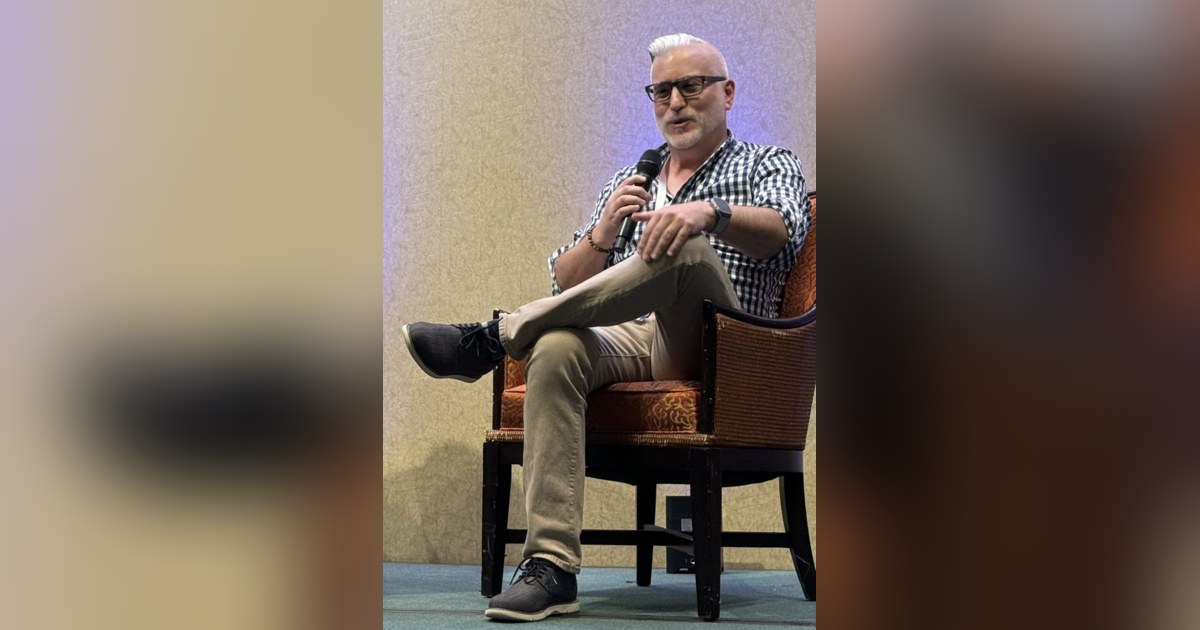
Kaufman & Company founder and CEO Daniel Kaufman said the retrade wave sweeping commercial real estate after the Federal Reserve's September rate increase is drawing a clear line between capital that can close and capital that cannot, and that family offices deploying their own money are positioned to step into the gap.
The Fed raised its benchmark rate by a quarter percentage point on Sept. 16, and minutes released Oct. 7 showed most officials believe another increase would likely be appropriate by year end. Since then, reporting by The Wall Street Journal and trade outlets including CRE Daily and Citybiz has described buyers pressing to renegotiate deals signed earlier in 2026, with some threatening to walk away. Trepp data cited in that coverage show 11.42% of CMBS loans were with special servicers in August, the highest share since February 2013.
Kaufman framed the retrade as a repricing of risk that was always embedded in the original deal. "A retrade is a buyer telling a seller the deal was really a bet on the rate," he said. "When the rate moves, the price moves, and everyone downstream waits. The sellers, contractors and towns counting on those projects carry that uncertainty. We invest our own capital, so our underwriting has to work without assuming the next Fed decision goes our way."
The implications extend well beyond the negotiating table. Because Kaufman & Company invests only its own capital and does not raise outside funds, its deals are not contingent on a financing window that can close when rates shift. That structure, Kaufman argues, favors long-term owners over buyers whose returns depend on a narrow band of borrowing costs, particularly in housing, where a stalled closing can push back construction and leave homes unbuilt.
"This is when family office capital should earn its keep," Kaufman said. "We are not looking to win by grinding down a seller who negotiated in good faith. We want to be the partner people can count on at the closing table, because on a housing deal a delay is not a line item; it is fewer homes for the people who need them."
The distinction matters for builders, sellers and municipalities that budget around project timelines. A retrade that stalls or collapses a transaction does not merely cost the parties a spread; it delays permits, disrupts contractor schedules and postpones the delivery of housing in markets already short of supply. Kaufman's contention is that certainty of execution has become a form of value in itself.
Kaufman & Company operates through 10 companies spanning housing development, design and construction, real estate consulting and venture investment. This month the firm announced BUILD 2030, a national initiative coordinating its housing, real estate and AI infrastructure work. The platform represents more than $2 billion in project value and more than 10,000 housing units across more than 25 years of building, lending and investing, according to thekaufmanco.com.
With officials signaling the possibility of further tightening before year end, the retrade pressure reported since September is unlikely to ease quickly. For sellers weighing whether to hold a signed contract or reopen it, the practical question becomes whose capital is not contingent on the next rate move, and Kaufman is betting that answer increasingly points to family offices writing their own checks.