
Texas drivers who carry the state's minimum auto liability insurance may believe they are fully protected, but a serious accident can quickly reveal a dangerous gap between what their policy pays and what injuries actually cost. The state's minimum coverage requirements—$30,000 for injuries to one person, $60,000 per accident, and $25,000 for property damage, known as 30/60/25—have not increased since 2011, even as medical expenses have climbed, according to (NewsUSA).
The implications are significant for anyone injured by another driver. A 2023 National Highway Traffic Safety Administration report estimated the average lifetime medical cost of a serious crash injury at $69,345, while the total economic cost reached $280,726 in 2019-dollar estimates. That total is more than nine times Texas's $30,000 minimum bodily injury liability limit. Once an at-fault driver's liability coverage reaches its policy limit, it generally will not pay additional expenses, even as medical bills, lost income, and rehabilitation costs continue to accumulate.
The risk grows when the responsible driver has little or no insurance. Research cited by the Insurance Research Council found that approximately one-third of U.S. drivers were uninsured or underinsured in 2023. In those cases, even a driver who was not at fault may find that the other party's coverage is insufficient to compensate everyone injured.
One protection many drivers overlook is uninsured and underinsured motorist coverage, or UM/UIM. This coverage can help eligible policyholders recover certain expenses when an at-fault driver has no insurance or insufficient liability coverage. Texas law generally requires insurers to include UM/UIM coverage unless the policyholder rejects it in writing. Drivers may decline the coverage to lower premiums without fully considering the financial consequences, making it important to understand the difference between liability coverage and UM/UIM protection.
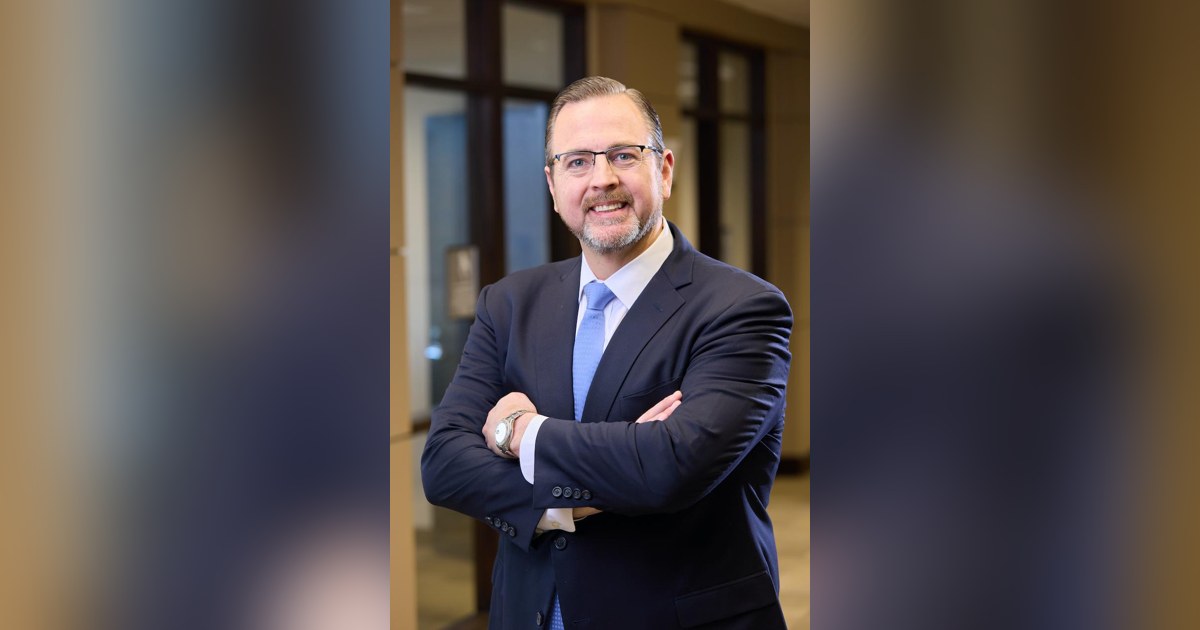
Ryan L. Thompson, founder and managing partner of Thompson Law, also known as 1-800-LION-LAW, has seen these challenges from both sides. Before representing injured individuals, Thompson spent years defending major corporations and gained firsthand experience with how insurance claims are evaluated and resolved.
Thompson Law encourages drivers to review their insurance declarations page, which summarizes coverage types, limits, and deductibles. Drivers should check whether their liability limits are adequate, whether they carry UM/UIM coverage, and whether additional protection makes sense for their circumstances. The Dallas-based personal injury firm, founded by Thompson, reports recovering more than $2.1 billion for injured people and families nationwide as of August 2026.
The broader implication is that meeting state minimums does not guarantee full protection. As medical and rehabilitation costs continue to rise faster than coverage requirements, drivers who rely solely on minimum liability insurance may face unexpected expenses after a serious crash. Taking time to understand a policy today could make a substantial financial difference tomorrow.